One of the most common misunderstandings surrounding gifting is the belief in a $19,000 annual giving limit per recipient. This limit actually refers to the amount that you can give without submitting any paperwork to the Internal Revenue Service (IRS). So what happens if you give over the $19,000 amount?
Gifting Beyond the Limit
Gifting an individual more than $19,000 requires the filing of Form 709 with the IRS; importantly, this does not mean that you owe any taxes. This form is designed to track your lifetime gift-and-estate tax exemption, which in 2026 is $15 million per person. Thus, any excess above $19,000 will be subtracted from your lifetime exemption.
If you’re married, this limit effectively doubles. Spouses can elect to “split” gifts, meaning a couple can give up to $38,000 to a single recipient in 2026 without dipping into either spouse’s lifetime exemption.
While it may appear tempting to skip filing Form 709, it is still important even if you are certain that you will never surpass the lifetime exemption. Filing Form 709 ensures that your gifts are disclosed and recorded, giving the IRS only three years to potentially challenge any gifts rather than an indefinite period. Additionally, Form 709 creates a paper trail for any interested parties of your recipient.
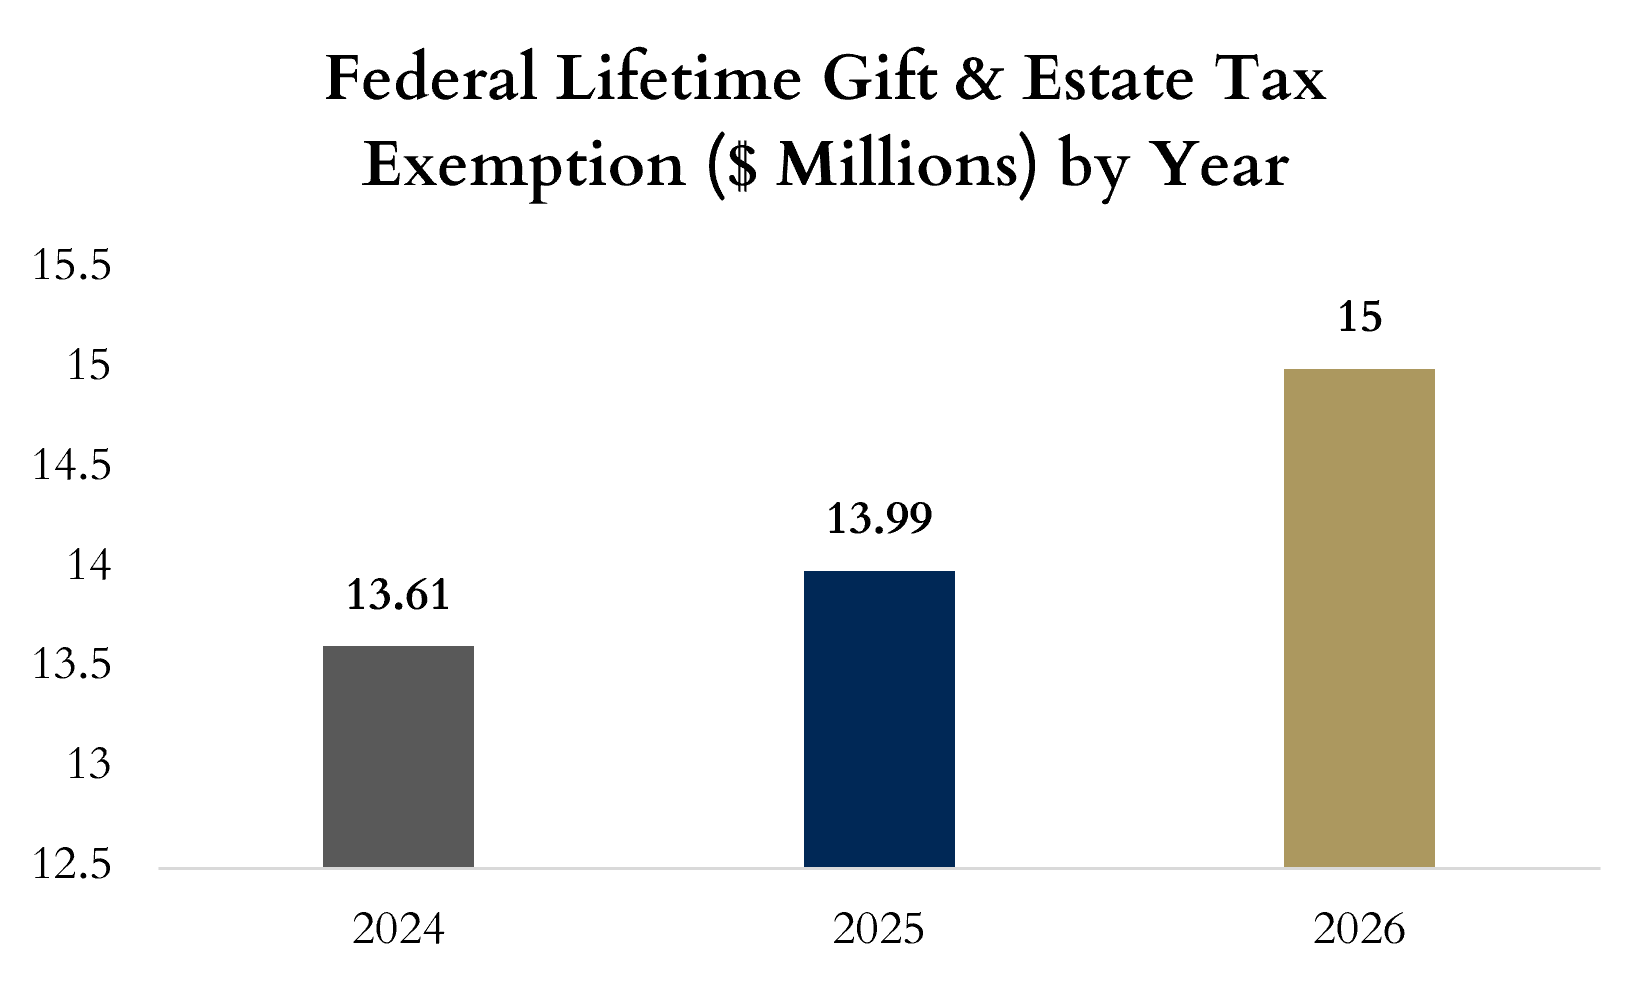
Education & Medical Gifting
Tuition payments made directly to a qualifying school are excluded from gift tax considerations. However, only tuition is excluded; room and board, books, and other supplies are still counted. Note that medical payments made directly to a medical provider on someone else’s behalf are also excluded from gift tax.
If planning any gifts to a 529 plan, it is important to be aware of the front-loading option for gifts. This rule permits up to five years’ worth of annual gifts to be given at once, meaning up to $95,000 per person in 2026. This election allows the money to be invested and begin compounding immediately rather than slowly trickling in each year.
One caution for grandparents funding 529 plans or making other gifts directly to grandchildren: these transfers can also trigger the generation-skipping transfer (GST) tax on top of ordinary gift tax rules if the GST exemption isn’t properly allocated on Form 709.
Large Capital Gains in the Estate
The classic advice is that any highly appreciated stocks should be left in your estate so that when your children inherit them, the basis receives a “step-up”. This means that they won’t owe capital gains tax, as all prior appreciation is no longer considered. While this is generally true, there are instances where a warm-hands approach may be more beneficial.
If your children or grandchildren have minimal income, they may be in a low or even zero tax bracket for capital gains. This means that you could gift them some of the assets now, and they could sell them without incurring much in taxes, allowing them to utilize the funds immediately.
Giving It All Away
Remember that once a gift is given, it cannot be taken back. In contrast, your retirement expenses aren’t going anywhere. So while the limit for gifting is high, especially for a married couple, it is vital to first understand how it factors into your plan.